UK Carbon Border Adjustment Mechanism (CBAM): compliance guide for importers
The Carbon Border Adjustment Mechanism (CBAM) is a carbon pricing framework designed to prevent carbon leakage by placing a carbon cost on certain imported goods. A CBAM mechanism already exists within the European Union, and the UK government is developing its own UK CBAM, effective from 1 January 2027, which will affect businesses importing certain carbon-intensive products.
Key takeaways
- The UK CBAM will be introduced on 1 January 2027.
- It’s designed to reduce carbon leakage by applying a carbon price to certain imported goods.
- The UK CBAM will initially apply to imports in the aluminium, cement, fertiliser, hydrogen, iron and steel sectors.
- Businesses importing affected goods should review supply chains, emissions data and compliance requirements.
What is the UK Carbon Border Adjustment Mechanism (CBAM)?
UK CBAM will place a tax on the importation of certain emission intensive goods into any part of the UK from countries with a lower or no carbon price. The tax will be based on the carbon emissions generated in production, adjusted to reflect the gap between the carbon price (the tax or equivalent paid) applied in the country of manufacture and the carbon price (tax due) applied in the UK. Time is now running out for businesses to check if they will be impacted, and to become CBAM ready from 1 January 2027.
Why is the UK introducing CBAM and how does it prevent carbon leakage?
The global approach to addressing carbon emissions is changing, with most major economies taking steps to decarbonise. As part of the UK’s commitment to reach net zero by 2050, the government has introduced regulations and rules, such as the UK Emissions Trading Scheme (UK ETS), which incentivises businesses to decarbonise by imposing a cost on carbon emissions. However, imported goods are not subject to the UK ETS, which can lead to variances in carbon pricing across the UK market.
With domestic emission regulations getting tougher, emission intensive companies may look to shift their operations to countries with more relaxed emissions laws. This will lead to ‘carbon leakage’– which remains a big piece in the puzzle to reach global net zero targets. A co-ordinated international approach would be needed to mitigate the risk of carbon leakage, but given that this will take time, and in line with the EU implementing its CBAM, the UK government is introducing a UK CBAM.
July 2026 update: new rules on CBAM rates and Carbon Price Relief (CPR)
The UK’s Carbon Border Adjustment Mechanism (CBAM) has taken a significant step towards implementation following the recent publication of the Carbon Border Adjustment Mechanism (Calculation of CBAM Rate and Determination of Carbon Price Relief) Regulations 2026, together with HMRC’s accompanying guidance.
Whilst earlier dialogue around CBAM focused largely on policy development, the latest regulations provide much greater detail regarding two of the most commercially important aspects of the regime:
- How future CBAM liabilities will be calculated.
- How importers may reduce those liabilities through claims for Carbon Price Relief (CPR).
For businesses importing goods within the sectors covered by CBAM, these developments represent an important shift from consultation to implementation ahead of CBAM’s commencement on 1 January 2027.
How UK CBAM works: emission reporting and tax calculation
Following the publication of draft legislation in April 2025 and further regulations and HMRC guidance published in July 2026, this is what we now know about how CBAM will work.
CBAM will place a carbon price on the most emission intensive industrial goods imported into the UK from the following sectors:

Specific ‘CBAM goods’ will be identified by through the use of existing commodity code (tariff codes applied to imported goods at the point of declaration).
Products from the ceramic and glass sectors will not be in scope of UK CBAM from 2027, as had initially been proposed, but will be considered for future inclusion.
CBAM will only apply to ‘CBAM goods’ which are imported in the course of business and any goods imported for non-business purposes will be outside of scope. CBAM liability will initially be calculated by reference to direct emissions embodied in CBAM goods, including relevant emissions embodied in certain precursor goods. The inclusion of indirect emissions has been delayed until 2029 at the earliest.
HMRC will set a CBAM rate for each CBAM sector based on the effective carbon price in the UK, which is the price paid by producers after accounting for the impact of free allowances and other reductions. The aim is to ensure that imported goods are subject to a carbon price comparable to that incurred by UK production.
Certain imported scrap products within the aluminium and iron and steel sectors, identified by relevant commodity code, will be excluded from UK CBAM. Partly because the risk of carbon leakage from using such products as input materials is low, and it would be difficult to distinguish between pre- and post-consumer scrap.
How to calculate UK CBAM liability
There will be two options to determine emissions embodied within imported goods for calculating UK CBAM liability. The liable person will be able to either:
- Use independently verified data on the actual emissions embodied within CBAM goods, or
- Use default values set per product by the government (the initial default values will be published ahead of 1 January 2027).
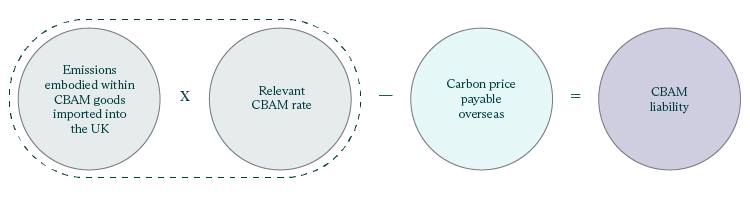
HMRC will set quarterly CBAM rates for each sector within the scope of CBAM. CBAM liability will then be calculated by multiplying the CBAM rate by the embodied emissions and deducting any overseas carbon prices that have already been paid (to avoid double taxation). Carbon Price Relief is covered in more detail below.
The calculation can be summarised as follows:
The tax point for determining the CBAM liability will depend on whether goods are subject to customs control. If they are, the tax point will be the date on which the goods are released. If not, the tax point will be the date the goods first enter the UK.
The ‘liable person’ for CBAM will generally be the importer of the goods for CBAM purposes. Where goods are not subject to customs controls, the liable person will be the person on whose behalf the goods are imported.
The ‘liable person’ must register with HMRC for CBAM if either the aggregate value of CBAM goods in the previous 12 months was £50,000 or more or it is expected to be more than £50,000 in the next 30 days. This threshold has been increased from the original proposal of £10,000.
Certain connected companies will be able to apply for group treatment, so that one company (the representative member) is responsible for submitting CBAM returns and paying the CBAM liability on behalf of the entire group.
Carbon Price Relief (CPR): reducing your UK CBAM liability
One of the most significant developments is the introduction of a more detailed framework for CPR.
The policy intention behind CPR is straightforward: where imported goods have already borne a qualifying carbon price outside the UK, that cost should be taken into account when calculating the UK’s CBAM charge.
The regulations establish the framework for:
- Determining entitlement to relief,
- Calculating the amount of relief available,
- Verifying claims, and
- Maintaining supporting evidence and records.
For businesses sourcing goods from jurisdictions that operate carbon pricing mechanisms, the value of CPR could be significant. However, the practical challenge may lie less in the calculation itself and more in gathering sufficient evidence to support a claim.
CBAM Carbon Price Verification Form: evidence requirements for CPR claims
As part of its latest guidance package, HMRC has introduced supporting documentation relating to Carbon Price Relief, including a Carbon Price Verification Form.
The form must be completed by an independent and accredited verifier of the installation that manufactured or processed the CBAM good and is intended to provide evidence supporting CPR claims.
The form captures information including:
- Installation and operator details,
- Carbon pricing scheme details,
- Emissions data,
- Carbon pricing adjustments, and
- Independent verifier information.
In practice, this means importers may need to work back through their supply chains to identify the relevant overseas installation and ensure the necessary verification can be obtained from an appropriately accredited third party.
For many businesses, this will require a level of engagement with overseas suppliers that has not previously been necessary for customs or indirect tax purposes.
CBAM record keeping and supporting evidence
The latest regulations and accompanying HMRC guidance place significant emphasis on record keeping and evidential requirements.
Businesses should now take active steps to determine:
- What information they currently receive from suppliers,
- Whether overseas carbon pricing information is available,
- Whether supplier contracts provide adequate rights to obtain evidence,
- Whether internal systems can capture and retain relevant data, and
- How evidence will be retained to support future CPR claims.
For many importers, CBAM compliance will not simply be about calculating a liability. The ability to obtain, verify and retain evidence supporting CPR claims may prove just as important in managing future CBAM costs.
UK CBAM returns, registration deadlines and penalties
The first CBAM return will be for the 12 months from 1 January to 31 December 2027 and the return and any payment will be due by 31 May 2028. The draft legislation provides that from 1 January 2028 CBAM accounting periods will be based on calendar quarters with returns and payments due on the last working day of the second month after the end of the accounting period. HMRC has the power to change the accounting periods and deadlines and has said it may do so for the first quarterly accounting periods to support businesses with the transition to quarterly accounting.
Businesses that are liable to the CBAM will need to submit CBAM returns for each prescribed accounting period, even if the liability to the CBAM is nil. Businesses will be able to deregister if they are incorrectly registered, or if they have not met the CBAM registration tests in the previous 12 months. The government has confirmed that tax agents will be able to submit CBAM returns on behalf of liable persons. There are no plans for a CBAM deferment scheme.
Penalties will apply for compliance errors, for example, failure to register for the CBAM, failure to submit CBAM returns and failure to keep records. The plan is for HMRC to use existing powers and penalties, including a general regulatory penalty for offences that are specific to the UK CBAM. The government is looking to align with the VAT penalty points system as far as possible for late submission of CBAM returns and late payment.
Who will be affected by the UK CBAM?
If you’re a UK business importing emission intensive industrial goods into the UK for business purposes, you may fall within the scope of CBAM. Affected businesses must consider the impact of the additional reporting requirements, and the cost of charges levied on them under CBAM, and plan accordingly. Businesses should review supply chains in advance of implementation to mitigate the potential CBAM liability.
Preparing for UK CBAM: five steps businesses should take now
With CBAM implementation approaching, businesses importing potentially affected goods should begin preparing by:
- Identifying whether imported goods fall within the sectors covered by CBAM by reviewing commodity codes and import data.
- Determining who is the liable importer within the supply chain.
- Assessing whether overseas carbon costs may qualify for Carbon Price Relief and reviewing the evidence required to support claims.
- Engaging with suppliers regarding emissions and carbon pricing information.
- Establishing processes to retain relevant data and documentation.
Importers that leave these questions until CBAM goes live may find that historic information is difficult to obtain retrospectively.
How Saffery can help with UK CBAM compliance
The introduction of CBAM will present challenges for those operating within the affected sectors, and preparing for the changes is vital.
We can support you in the following ways:
- Reviewing the goods currently being imported by reference to the commodity codes within scope of CBAM,
- Assessing the potential CBAM liability and registration requirements,
- Assisting with developing internal processes and systems readiness for the implementation of CBAM, and
- Providing insights from government departments whom we are liaising with.
In addition to helping businesses understand the tax implications of CBAM and identifying ways to reduce future CBAM costs, we can also support engagement with suppliers to better understand embedded emissions and explore opportunities to source lower-emission products, helping to advance broader sustainability objectives. Our sustainability and ESG team can help your business get started.
If you have any questions or would like to discuss how CBAM may affect your business, please get in touch.
FAQs
What is CBAM?
CBAM stands for Carbon Border Adjustment Mechanism. It’s a policy designed to place a carbon cost on certain imported goods to ensure that overseas producers face similar carbon pricing pressures to domestic producers.
What does Carbon Border Adjustment Mechanism mean?
The Carbon Border Adjustment Mechanism (CBAM) is intended to prevent ‘carbon leakage’, where businesses move production to countries with less stringent environmental regulations. It helps create a level playing field between imported goods and domestically produced goods.
What is the UK CBAM?
The UK Carbon Border Adjustment Mechanism is a proposed carbon pricing measure that will apply to certain imported goods entering the UK. It’s being developed separately from the EU CBAM and is intended to support the UK’s decarbonisation objectives.
When will the UK CBAM come into effect?
The UK CBAM will be introduced on 1 January 2027. It will place a carbon price on specified imported goods to align their carbon costs with those faced by UK producers.
What does UK CBAM for UK importers?
UK importers of goods covered by the Carbon Border Adjustment Mechanism (CBAM) may face new reporting, record-keeping and compliance requirements. Businesses will need to understand the carbon emissions associated with imported products and may need to account for any carbon price differences between the UK and the country of origin.
How can businesses prepare for CBAM?
Businesses should review their supply chains, identify potentially affected imports, assess emissions data availability and monitor regulatory developments to understand future compliance obligations.
Contact us
Partner, Edinburgh
Key experience